South Africa's new vehicle market has extended its winning streak through most of 2026, with the National Association of Automobile Manufacturers of South Africa reporting year to date sales of 430 883 units by the end of August, an increase of 12,6% on the same period last year.
Yet a closer look at the data from Naamsa, TransUnion and WesBank suggests the real story is not simply new cars gaining ground while the secondhand market falls away, but a market being reshaped by affordability pressure, a wave of competitively priced Chinese brands and a level of uncertainty around resale values that has already prompted one of the country's largest vehicle financiers to set aside extra provisions against future losses.
Naamsa's monthly releases tell a consistent story of growth. January opened the year with 50 073 units sold, up 7,5% on January 2025. By the end of February, cumulative sales had reached 103 918 units, a 9,8% increase on the same two months of the previous year and the first time the market had broken through the 100 000 mark by that point in a decade.
March brought the best performance for that month since 2007, with 58 060 units sold, a jump of 17,3%. April and May each recorded their strongest showings since 2013, at 47 979 and 51 071 units respectively, up 13,0% and 12,8% year on year. June, at 54 482 units, was the best June since 2007, up 15,3%, while July and August each pushed past the 57 000 unit mark, rising 11,9% and 11,4% respectively, even as vehicle exports came under sustained pressure, falling by close to 12% in August alone.
Naamsa has attributed the sustained demand to a combination of moderating inflation, a more stable interest rate environment and improving vehicle affordability, though the industry body has repeatedly cautioned that the outlook for the remainder of the year remains uncertain given still elevated living costs and borrowing pressures on households.
Safe and inexpensive cars for students - click here
Where the picture becomes more nuanced is on the used vehicle side. Rather than a straightforward decline, TransUnion's Mobility Insights reports show the relationship between new and used vehicle registrations shifting in two different directions over the course of the year.
In the first quarter, the ratio of used to new vehicle registrations fell to 2,3, the lowest level TransUnion has recorded, with new vehicles' share of total registrations climbing to 31%, up from 23% in the final quarter of 2025. That amounted to a meaningful swing toward new vehicles in a single quarter. By the second quarter, however, the trend partially reversed, with the used to new ratio climbing back up to 2,7, even as new passenger vehicle sales grew 15,8% year on year, the strongest quarterly growth in three quarters.
The structural story beneath those used car numbers is worth pausing on. Buyers are clearly trading down. The Suzuki Swift became the fastest-selling used model in the country, turning over in just 26 days on average. The Hyundai Grand i10 broke into the top ten for the first time, while the Toyota Fortuner slipped down the rankings.
Ayesha Hatea, director of research and consulting at TransUnion Africa, has described this less as consumers abandoning car ownership and more as a shift toward pragmatism, with buyers increasingly weighing overall value rather than simply chasing the lowest sticker price. That caution is also visible in TransUnion's purchase intent figures, which slipped from 22% in the first quarter to 19% in the second, with the decline most pronounced among lower and middle income households.
Taken together, the data does not support a simple narrative of new car growth coming at the direct expense of a shrinking used market. What it does show is total transaction volumes holding up, with used vehicles still accounting for the majority of registrations, while the composition of demand shifts toward more affordable options wherever they can be found, whether that means a budget conscious buyer choosing a lower priced new model over an ageing used one, or a financially stretched household delaying an upgrade altogether.
Starting or expanding your business and in need of a bakkie – click here
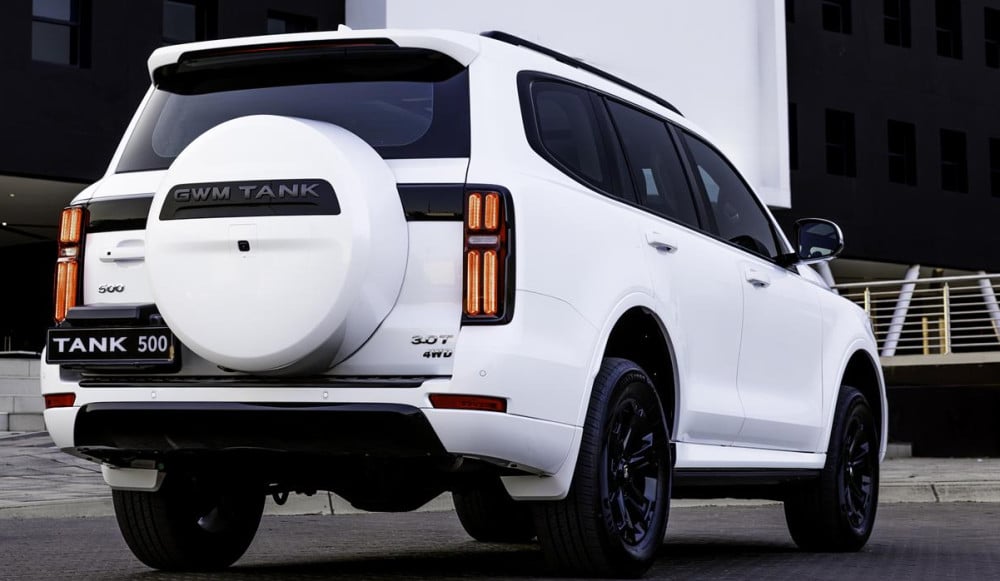
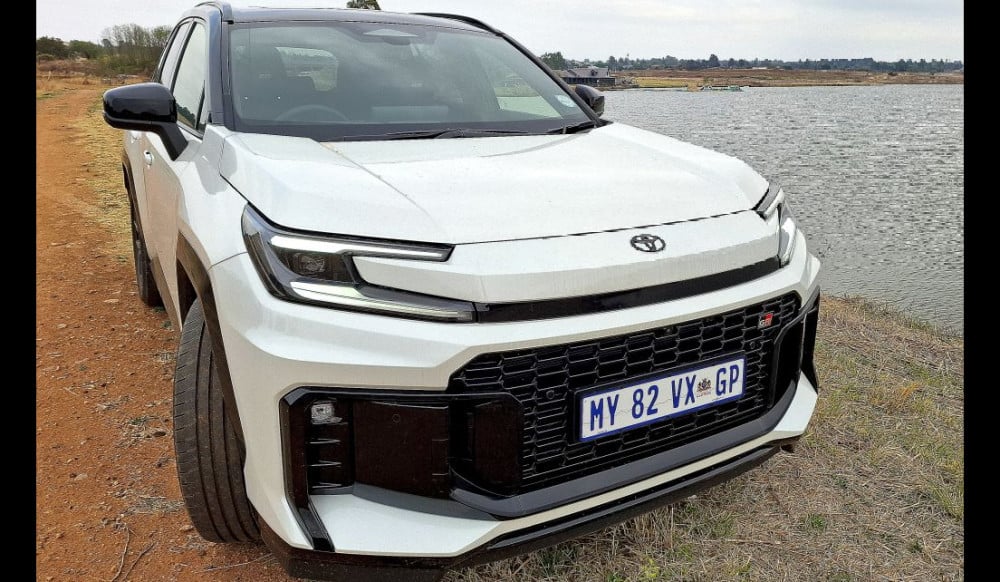
The clearest driver of that shift has been the rapid rise of Chinese vehicle brands. According to the Cars.co.za Industry Report for 2026, which draws on TransUnion credit data and Absa's analysis of 2,56 million finance applications, Chinese brands recorded sales growth of 72% year on year in the second quarter and now account for roughly 22% of the passenger and light commercial vehicle market. Their share of SUV finance applications alone has risen from 19% to 40% since 2023, eating into territory once dominated by established manufacturers.
That growth has not gone unnoticed by the finance houses that underwrite much of the country's vehicle buying. FirstRand chief executive Mary Vilakazi said increased competition in the new vehicle market has placed structural downward pressure on the price of secondhand vehicles, as buyers who might once have settled for an older used car increasingly opt for a cheaper new one instead.
"The prices of vehicles in South Africa have come down structurally due to increased competition," Vilakazi said, adding that the group was concerned about what would happen to used vehicle values when current owners eventually come to sell. As a direct result, WesBank has increased its provisions for losses arising from loan defaults and the resale of repossessed vehicles, specifically to account for this new resale risk.
WesBank has gone further, arguing that the future resale value of a vehicle will increasingly need to reflect not only its age and mileage but the pricing, specification and competitive landscape of the new vehicle market at the point it eventually changes hands, rather than being estimated from historical depreciation patterns alone.
In practice, that means a car bought today could be worth meaningfully less in three or four years simply because a manufacturer cuts new prices or a new competitor enters the segment, regardless of how well the vehicle itself has been looked after.
The picture on the ground is not uniformly bleak for the brands driving this disruption. A sampling of two year old Chinese models found some, including the Chery Tiggo 4 Pro, had depreciated by only 7,1% on the manual variant and 11,1% on the automatic over two years, comparing favourably with equivalent BMW, Hyundai, Suzuki, Volkswagen and Toyota models. That suggests the anxiety among financiers is less about a uniform collapse in used values and more about the unpredictability that price competition introduces into a market that has traditionally priced risk on decades of stable depreciation curves.
Can I afford it – find out with this handy Finance Calculator
The question of how new car price cuts affect used car values is one that every dealer in the country has had to grapple with. The mechanics are straightforward enough. When someone walks onto a used car lot, the first comparison they make is between a nearly new model and its brand-new equivalent.
If manufacturers are cutting prices or throwing generous incentives at buyers, that gap narrows sharply. Faced with a small difference, most buyers will take the new car every time. It has zero mileage, a full warranty and often better finance terms. The used car then must be repriced downward to remain attractive, and the newer it is, the harder the hit, because it was originally sold on the strength of that price gap.
Some will recall the massive disruption created by Jim Miller who, as CEO of Samcor during the period post-apartheid when Ford was in the process of re-entering the market, drastically cut prices on entry-level Ford and Mazda models – wreaking havoc in the used car arena and simply wiping out resale values for owners who bought prior to the discounts.
There is a supply-side consequence too. News of new car discounts tends to push owners who were already thinking about a change to act sooner rather than later. Their existing vehicles flood into the used market. When stock rises but buyer demand does not rise in step, dealers find themselves sitting on inventory and trade-in offers get trimmed accordingly.
The more insidious effect, though, is on expectations. Once manufacturers fall into a habit of frequent, large discounts to shift metal, buyers learn to wait. Urgency evaporates. Used car buyers, meanwhile, start factoring future new car price cuts into what they are willing to pay, which drags offers down further. A self-reinforcing cycle takes hold in which discounts push used values lower, consumers become more price sensitive, and the pressure for yet more discounts builds.
For now, the numbers point to a new vehicle market in genuine, broad based growth, a used vehicle market that has shifted rather than shrunk, and a finance industry recalibrating how it prices risk in a segment where the ground is moving faster than the historical models were built to handle.
Colin Windell for Colin-on-Cars in association with
proudly CHANGECARS